
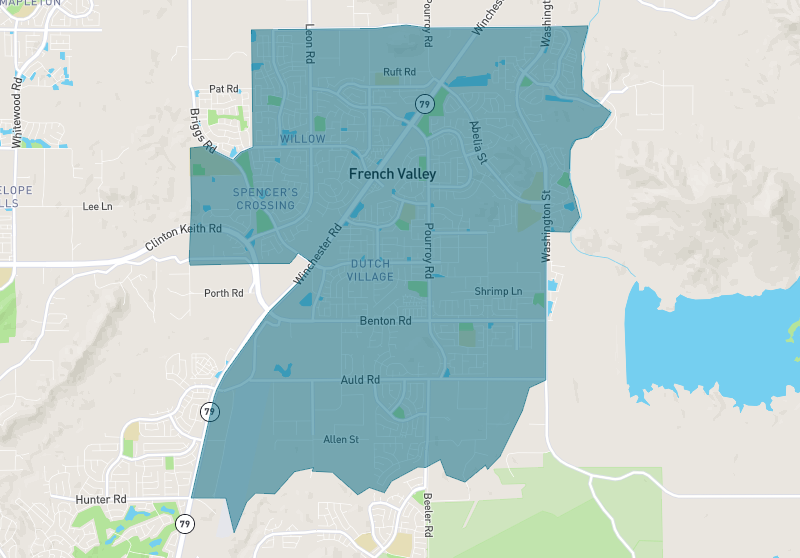
Yes, most newer homes in French Valley have both a Mello-Roos special tax and an HOA fee, and together they can add several hundred dollars a month on top of your mortgage. Older tracts often have little or no Mello-Roos, so two homes at the same price can come with very different monthly payments.
If you're moving here from the Bay Area or the coast, this is the line item that seems to be left out the most. The list price looks like a gift compared to what you're used to. Then the lender's tax estimate comes back closer to 2% than 1%, and suddenly the math feels different. It's not a scam and it's not a dealbreaker. You just need to know what you're looking at before you write the offer, not after.
What is Mello-Roos?
Mello-Roos comes from a 1982 California law that lets a county, city, school district or water district form a Community Facilities District (CFD). The CFD sells bonds to pay for the things a brand-new neighborhood needs (roads, sewer lines, schools, parks, fire stations), and the homeowners inside it pay the bonds back through a special tax on their property tax bill.
Three things make it different from your regular property tax:
- It's not based on your home's value. It's a set amount from the district's formula, so a $600K house and a $700K house on the same street may pay the same.
- It isn't treated like regular property tax for income taxes. Ask your CPA before you count on deducting it.
- It shows up as its own line. On a Riverside County tax bill, look under special assessments for anything labeled CFD, followed by a district number and an amount.
Why French Valley has so much of it
French Valley isn't a city. It's unincorporated Riverside County, and most of it was built in the last 20 years. New neighborhoods without a city budget behind them get their infrastructure paid for through CFDs, and the county is still forming them. In September 2025 the Board of Supervisors formed a new district for a 48-home French Valley tract, and the county's list of active maintenance districts reads like a map of the area: Winchester Ranch, French Valley South, Brisa Pointe, Springbrook and more.
The county isn't the only one. Eastern Municipal Water District, Valley-Wide Recreation and Park District and school districts have formed their own CFDs here too. One house can have several CFD lines stacked on a single bill.
What it looks like in real dollars
A useful rule of thumb out here:
- Older homes without Mello-Roos: usually around 1.1–1.25% of the purchase price per year. (Prop 13's 1% base, plus voter-approved bonds.)
- Newer construction: often close to 2%. Lennar's Amber Valley community in French Valley lists an approximate tax rate of 2%, for example.
Here's what that gap does on a $650,000 home:
Tax rate | Per year | Per month | |
|---|---|---|---|
Older tract | ~1.15% | ~$7,475 | ~$623 |
Newer tract with Mello-Roos | ~2.0% | ~$13,000 | ~$1,083 |
Difference | ~$5,525 | ~$460 |
That's about $460 a month that has nothing to do with your interest rate. You'll see published figures like "French Valley's effective tax rate is 1.11%". That's an average across every home, including long-time owners whose assessed values are far below today's prices. It isn't what you'll pay on a recent purchase.
Does Mello-Roos ever go away?
Sometimes. BUT it depends on what kind of district it is.
- Bond-funded districts end when the bonds are paid off. The Notice of Special Tax tells you how many years are left. These often run 20 to 40 years from when the district was formed, so a home built in 2008 may be a lot closer to the finish line than one built in 2024.
- Maintenance districts are a different animal. Many of Riverside County's newer French Valley districts have an "M" in the name (like CFD 25-6M or 19-2M Winchester Ranch). They pay for ongoing upkeep (landscaping, parks, streetlights), and the county lists them as an ongoing cost. Plan on those sticking around unless the notice says otherwise.
- More bonds can be issued. If a district hasn't sold all the bonds it's authorized to sell, it can issue more later, which keeps the tax on the bill longer.
The only reliable answer for a specific house is that district's own notice. Anyone who gives you a payoff year off the top of their head is guessing.
This is why it is my standard to request a copy of the seller's annual tax bill when my buyers are considering purchasing the house.
HOA fees in French Valley
The HOA side is much simpler. It's mostly a question of what kind of home you're buying:
- No HOA: they exist, even in new construction. A KB Home on Slough Road listed this year was advertised as no-HOA.
- Single-family homes in master-planned communities: commonly around $150 a month. Taylor Morrison's Siena neighborhoods (Rosa, Azul, Viola) list $152, and Lennar's Amber Valley lists about $153.
- Townhomes: much higher, because the HOA covers and maintains more. Recent listings at Oliva at Siena showed $449 to $647 a month.
One thing that trips people up: low HOA dues don't always mean low costs. In some tracts, the parks and landscaping an HOA would cover elsewhere are paid through a county maintenance district on your tax bill instead. Add the HOA and the CFD lines together before you compare neighborhoods.
And if you have birds (or any pets beyond a dog or cat), read the CC&Rs before you fall in love. HOA rules on aviaries, outdoor enclosures and noise vary a lot from one community to the next. I covered that in detail in my aviary and zoning blog.
How to find the real numbers before you make an offer
- Check the Natural Hazard disclosure. On a resale, California requires the seller to provide this disclosure report to you. It shows the annual amount of mello-roos if applicable, along with fire, earthquake and flood hazards that may pertain to the specific property.
- Pull the current tax bill from the Riverside County Treasurer-Tax Collector's property search. Scan the special assessments for every CFD line. Each one lists a phone number for the district that levies it.
- Read the property tax disclosure report that comes in your escrow package. Don't just sign it.
- Get the HOA documents early: current dues, transfer fees, reserve study, any special assessments, and the CC&Rs.
- Make sure your lender qualifies you on the full number, Mello-Roos and HOA included, not just principal, interest and a generic 1.25% tax estimate.
- Brace for the supplemental bill. After you close, the county reassesses at your purchase price and sends a separate supplemental tax bill straight to you, not to your lender.
So is it worth it?
For a lot of families, absolutely. Mello-Roos is the reason French Valley has newer streets, parks every few blocks and newer schools, and many tracts here are in Temecula Valley Unified. You're paying for something tangible and real.
What I don't want is for anyone to compare homes on price alone. A slightly more expensive older home at a 1.15% tax rate can cost less every month than a cheaper new build at 2%. Compare monthly cost, not list price.
Have you been surprised by a tax bill since moving to the Temecula Valley? Or are you trying to figure out whether a specific French Valley home is worth it? Send me the address and I'm always happy to run the real monthly numbers with you. Check out my Temecula vs. Murrieta vs. French Valley comparison too.
Check out this article next